Skip to content

Discover Baldwin County, Alabama: A Golfer’s Paradise

Discover Baldwin County, Alabama: A Golfer’s Paradise

Considering a move to the area? Explore Fairhope, Daphne and Spanish Fort community information and search Eastern Shore homes for sale.
Golf course in Baldwin County, Alabama

For golfers, Baldwin County, Alabama, is the ultimate destination where lush greens, stunning views, and a thriving golf culture come together. Nestled along the Gulf Coast, this hidden gem offers more than just picturesque courses—it’s the perfect place to live the dream of golfing year-round. Whether you’re an avid player or looking for a home that embraces the golf lifestyle, Baldwin County blends scenic courses with golf-centric communities for an experience like no other.

Top 3 Golf Courses in Baldwin County

The top 3 golf clubs in Baldwin County, Alabama, are typically recognized for their exceptional course design, amenities, and overall golf experience. Based on reputation, membership options, and the golfing experience they provide, these are the top three:

Number One: Lakewood Golf Club at The Grand Hotel

Tucked away in Point Clear, Lakewood Golf Club is more than just a golf course—it’s a prestigious destination. As part of the renowned Robert Trent Jones Golf Trail, Lakewood features two stunning courses: the Azalea and the Dogwood. Both courses are celebrated for their rolling hills, Southern pines, and breathtaking landscapes.

Why it’s Top-Rated: Lakewood Golf Club is arguably the most prestigious course in Baldwin County. As part of the renowned Robert Trent Jones Golf Trail, it offers two breathtaking 18-hole courses: the Azalea and Dogwood courses. The course is known for its stunning views, historic charm, and challenging fairways that wind through Southern pines.

Amenities at Lakewood include a state-of-the-art fitness center, multiple swimming pools, 10 hydro-courts, and dining options, with access to the historic Grand Hotel Golf Resort & Spa.

Number Two: Steelwood Country Club (Loxley)

Why it’s Top-Rated: Steelwood is a private, members-only club designed by 1976 U.S. Open Champion Jerry Pate. The course, spanning over 7,000 yards, features natural elevation changes and stunning views of Steelwood Lake. Known for its exclusivity and challenging play, Steelwood is ideal for avid golfers who want a high-end experience.

Number Three: Kiva Dunes Golf Club (Gulf Shores)

Why it’s Top-Rated: Consistently ranked as one of Alabama’s best public courses, Kiva Dunes offers an exceptional golfing experience right on the Gulf Coast. The course is challenging but playable for golfers of all levels, and it boasts stunning views of the Gulf of Mexico. Kiva Dunes has hosted PGA and LPGA events and is a favorite for visitors to the area.

These three courses offer the best mix of design, beauty, and challenge, making them the standout golf destinations in Baldwin County. Whether you’re looking for a world-class resort course or a private, exclusive membership experience, or one of the best public courses in Alabama, these clubs represent the top choices in the region.

Your Dream Home on the Green

Fairhope: A Golfer’s Paradise with Charm, History, and Art

Fairhope, Alabama, is a vibrant community where culture, golf, and history blend seamlessly. Stroll along the picturesque streets, where you’ll find an eclectic mix of boutiques, galleries, and restaurants, offering a delightful combination of Southern charm and modern flair.  Each year, the town comes alive during its renowned Annual Art Festival, a celebration of local and national artists.
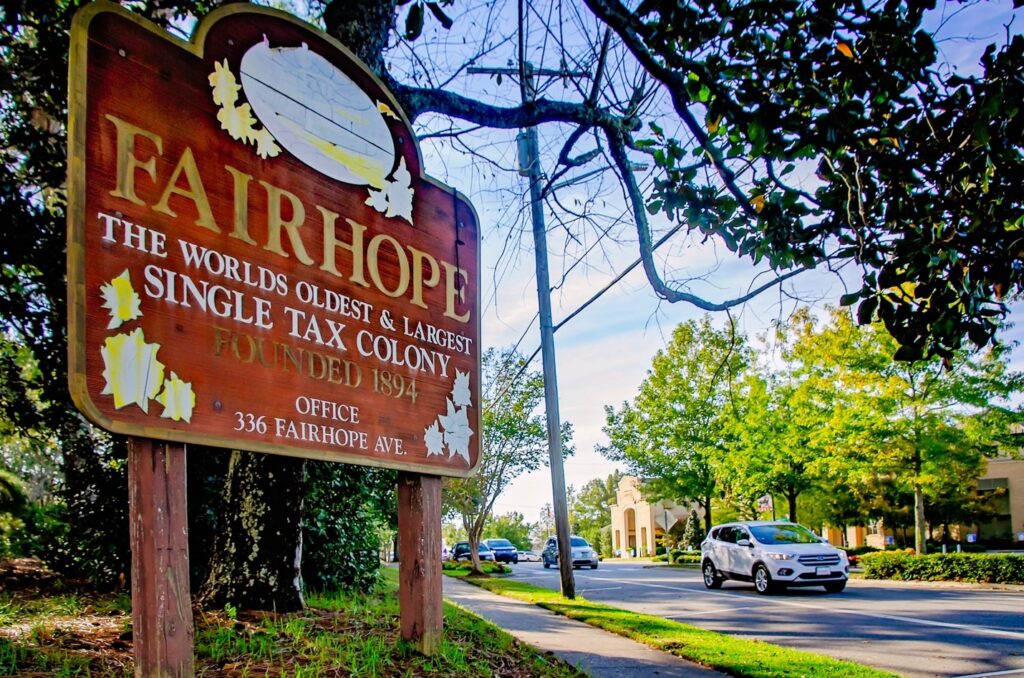

Founded in 1894 as the world’s oldest and largest single tax colony, Fairhope was established on the principle that land should be taxed in a way that benefits the entire community. This pioneering tax model continues to shape the town’s forward-thinking culture today.

The blend of stunning views, rich history, and vibrant arts scene make Fairhope not only an incredible place to live but also a haven for golfers who want a home near world-class courses with all the benefits of small-town charm and big-town culture.


Point Clear Woods (Fairhope)
Point Clear Woods golf community in Fairhope, AlabamaPoint Clear Woods is the pinnacle of Southern luxury, offering a serene, gated community where privacy and tranquility meet world-class golf. This exclusive neighborhood is known for its majestic oak trees and expansive lots, providing a peaceful haven for those seeking both beauty and serenity.


Residents of Point Clear Woods also enjoy direct access to Lakewood Golf Club, with the course just a short walk away, making it easy to spend your afternoons teeing off.

A prime example of what Point Clear Woods offers is the listing at 17342 Wildwood Court, a 5-bedroom, 4.5-bathroom estate spanning over 5,400 square feet. This Southern-style home blends luxury with charm, featuring a peaceful cul-de-sac location and easy access to Lakewood Golf Club, making it a perfect choice for golfers.

Another stunning home in the area, 6120 Oakwood Lane, boasts 4 bedrooms and 4 bathrooms, combining Southern craftsmanship with modern style. This home offers tranquil surroundings and plenty of space, ideal for those who want both comfort and access to world-class golf.

Point Clear: A Community Like No Other

Exclusive Access to Lakewood Golf Club
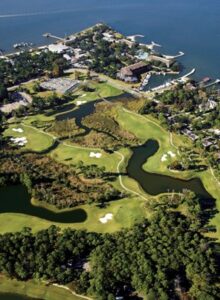
Residents of Point Clear Woods enjoy the unique privilege of having access to Lakewood Golf Club, one of the most prestigious golf courses in the area. While membership is not automatically included with property ownership, residents can apply for membership, which provides unlimited access to golf, tennis, swimming, and the club’s fitness facilities.


Architectural Elegance
Homes in Point Clear Woods are designed to complement the area’s natural beauty. The architecture reflects Southern charm with expansive layouts, high ceilings, and large windows offering stunning views of the surrounding landscapes.

Diverse Community
Point Clear is a welcoming community, great for everyone. Located just minutes from highly rated schools, shopping, marinas, and beaches, the neighborhood offers easy access to everything you need. It’s been celebrated for its strong community spirit and family-friendly atmosphere, earning accolades such as “2022 Best Places to Raise a Family in Baldwin County” by Niche.com. 
For those who love outdoor recreation, Point Clear is an ideal location. Residents have access to numerous parks, trails, and Mobile Bay, making it perfect for activities like fishing, boating, and enjoying the great outdoors. Whether you’re looking for a peaceful retreat or an active lifestyle, this neighborhood offers something for everyone.


As Neighborhood Scout puts it, “If you are planning to retire in Alabama, Point Clear should be on your must-see list. For many reasons, it may be considered a retiree’s dream neighborhood.” Read more


Point Clear Market Data
The median listing price in Point Clear as of April 2025 is $1.1M. According to Realtor.com, Point Clear was considered a buyer’s market in April 2025. So now is a good time to be teeing up to find your dream property in one of these premier golfing communities.

As of April 2025, there were 128 homes for sale in Point Clear, ranging from $45.8K to $7.5M. However, only 2 homes were available in Point Clear Woods—both listed by Ashurst Niemeyer Real Estate—making it an extremely sought-after community in the area.
 

Why Baldwin County?

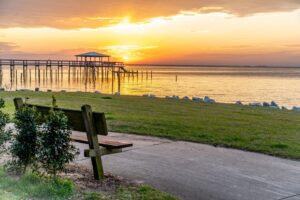
Beyond the greens, Baldwin County offers a high quality of life. The relaxed coastal lifestyle features dining, shopping, and cultural events that ensure there’s always something to enjoy. Whether it’s a day at the beach, a stroll through historic Fairhope, or a night out at a local restaurant, Baldwin County has it all.

Ready to Live the Golfing Dream?

If you’re ready to make golf more than just a game and turn it into your lifestyle, Baldwin County has the perfect home waiting for you. Whether you’re eyeing a property on a world-class course or a luxurious home within a golf-centric community, Ashurst Niemeyer Real Estate is here to help you find your dream home. Let us guide you to the perfect spot where stunning fairways and breathtaking views are just steps from your front door. Reach out today and discover why Baldwin County is a golfer’s paradise!

16 Golf Courses in Baldwin County, Alabama

Bay Minette

Holly Hills Municipal Golf Course – A 9-hole, 3,116-yard course offering an affordable and relaxed golfing experience.

Daphne

TimberCreek Golf Club – A 27-hole championship course designed by Earl Stone, featuring scenic fairways and challenging layouts.

Lake Forest Golf Club – A 27-hole facility with a mix of 18-hole and 9-hole courses, offering a variety of golfing experiences.

Fairhope

Lakewood Golf Club – Lakewood Golf Club is arguably the most prestigious course in Baldwin County. As part of the renowned Robert Trent Jones Golf Trail

Rock Creek Golf Club
Located in Fairhope, Rock Creek Golf Club offers a gorgeous 18-hole course designed by Earl Stone. The course features winding fairways and stunning vistas that provide both a challenge and a serene experience.

Quail Creek Golf Course – An 18-hole course offering a friendly environment and well-maintained fairways.

 Loxley

Steelwood Country Club stands out as a premier golfing destination in Baldwin County, offering a blend of challenging play, natural beauty, and exclusive amenities. If you’re considering a golfing lifestyle in the area, Steelwood is a club worth exploring.

Foley

GlenLakes Golf Club – A 27-hole course offering a mix of water features and rolling hills, providing a blend of beauty and challenge.

Gulf Links Golf Center – An executive-style 18-hole course with a par 64 layout, suitable for golfers of all skill levels.

Gulf Shores

Craft Farms Golf Resort – Home to two 18-hole championship courses: Cotton Creek and Cypress Bend, both designed by Arnold Palmer.

Gulf Shores Golf Club – An 18-hole, par 71 course offering a traditional golfing experience.

Kiva Dunes Golf Club – An 18-hole course ranked among Alabama’s best public courses, offering stunning Gulf Coast views.

Peninsula Golf & Racquet Club – A 27-hole course nestled in a tranquil, wooded setting, providing both challenge and beauty.

Orange Beach

Orange Beach Golf Center – Features a 9-hole, par 3 course, lighted driving range, and practice facilities, catering to golfers of all levels.

Spanish Fort

Fairways Indoor Golf Club in Spanish Fort offers a state-of-the-art facility with high-definition golf simulators, allowing players to enjoy the sport indoors. The facility provides an experience above and beyond what is seen on a traditional outdoor course.

Elberta

The Preserve at Soldiers Creek– An 18-hole championship course offering a peaceful combination of natural beauty and challenging play.


Whether you’re a seasoned golfer or a beginner, Baldwin County offers a diverse range of courses to suit every skill level and preference. From the historic designs at Lakewood Golf Club to the coastal challenges at Kiva Dunes, there’s a course waiting for you to tee off. If you are considering a move to the area, explore our Eastern Shore community guide or search homes for sale in Baldwin County.

What’s the Difference between an Appraisal and a Home Inspection?

Home Inspection versus Appraisal

What’s the Difference between an Appraisal and a Home Inspection?

Quick answer: A home appraisal estimates a property’s market value, often for the mortgage lender. A home inspection evaluates the home’s condition and identifies issues a buyer may want to investigate. They serve different purposes, and an appraisal does not replace an inspection. For more guidance, read our Eastern Shore home-buying guide or search homes for sale in Fairhope, Daphne and Spanish Fort.

If you’re planning to buy a home, an appraisal is an important step in the process. It’s a professional evaluation of the market value of the home you’d like to buy. In most cases, an appraisal is ordered by the lender to confirm or verify the value of the home prior to lending a buyer money for the purchase. It’s also a different step in the process from a home inspection, which assesses the condition of the home before you finalize the transaction. Here’s the breakdown of each one and why they’re both important when buying a home.

Home Appraisal

The National Association of Realtors (NAR) explains:

“A home purchase is typically the largest investment someone will make. Protect yourself by getting your investment appraised! An appraiser will observe the property, analyze the data, and report their findings to their client. For the typical home purchase transaction, the lender usually orders the appraisal to assist in the lender’s decision to provide funds for a mortgage.”

When you apply for a mortgage, an unbiased appraisal (which is required by the lender) is the best way to confirm the value of the home based on the sale price. Regardless of what you’re willing to pay for a house, if you’ll be using a mortgage to fund your purchase, the appraisal will help make sure the bank doesn’t loan you more than what the home is worth.

Appraisal results can be especially important when the agreed purchase price differs from the appraised value. Market conditions change over time, so buyers should review the appraisal, discuss any gap with their lender and real estate professional, and understand their options under the purchase agreement.

However, the lender will only allow the buyer to borrow based on the value of the home. This is what helps keep home prices in check. If there’s ever any confusion or discrepancy between the appraisal and the sale price, your trusted real estate professional will help you navigate any additional negotiations in the buying process.

Home Inspection

Here’s the key difference between an appraisal and an inspection. MSN explains:

“In simplest terms, a home appraisal determines the value of a home, while a home inspection determines the condition of a home.”

The home inspection is a way to determine the current state, safety, and condition of the home before you finalize the sale. If anything is questionable in the inspection process – like the age of the roof, the state of the HVAC system, or just about anything else – you as a buyer have the option to discuss and negotiate any potential issues or repairs with the seller before the transaction is final. Your real estate agent is a key expert to help you through this part of the process.

Bottom Line

The appraisal and the inspection are critical steps when buying a home, and you don’t need to manage them by yourself. Let’s connect today so you have the expert guidance you need to navigate through the entire homebuying process.

A Quick Note From Judy Niemeyer

Welcome Fall, Judy Niemeyer

A quick note from Judy Niemeyer ~

Welcome to our Fall!  Mornings are beautiful with lower temperatures and beautiful skies.  Of course, you have to imagine fall leaves because in the South, our leaves stay green.  Can you believe that Thanksgiving is around the corner?

What a year 2020 has been. It has been a tough year for all of us.  It reminds me of a very bumpy road, smooth in sections, and then a rut comes and bumps us off our path. Covid-19 was the first issue that bumped us. Masks became the new norm. Then Sally struck us with unbelievable winds and destruction. Now, we sit back and see what is next. Is it another Covid-19 burst or just the flu? Who knows?

Thank goodness, our real estate market has been very active. Interest rates continue to be very low. It is a great time for people to sell and buy. A lender last week quoted a 30-year interest rate of 2.8% which is hard to believe. Even with these low interest rates, buyers are still very opinionated. Selling a home is not as easy as the general public thinks.


Let’s compare 2019 to 2020:

Presently we have 523 active homes on the market from Spanish Fort to Point Clear with 460 homes under contract.  If all of these homes close, 2020 will be an incredible real estate year.

If you have questions, please feel free to call me. I always love to hear from you!


Tax Advice if You Sold Your Home

Tax Implications of Selling a Home

Did You Sell Your Home After Making Improvements?

Keeping track of the cost of capital improvements to your home can really pay off on your tax return when it comes time to sell.

Tax Implications of Selling a Home

It’s no secret that finishing your basement will increase your home’s value. What you may not know is the money you spend on this type of so-called capital improvement could also help lower your tax bill when you sell your house.

Tax rules let you add capital improvement expenses to the cost basis of your home. Why is that a big deal? Because a higher cost basis lowers the total profit—capital gain, in IRS-speak—you’re required to pay taxes on.

The tax break doesn’t come into play for everyone. Most homeowners are exempted from paying taxes on the first $250,000 of profit for single filers ($500,000 for joint filers). If you move frequently, maybe it’s not worth the effort to track capital improvement expenses. But if you plan to live in your house a long time or make lots of upgrades, saving receipts is a smart move.

What Counts As a Capital Improvement?

Although you may consider all the work you do to your home an improvement, the IRS looks at things differently. A rule of thumb: A capital improvement increases your home’s value, while a non-eligible repair just returns something to its original condition. According to the IRS, capital improvements have to last for more than one year and add value to your home, prolong its life, or adapt it to new uses.

Capital improvements can include everything from a new bathroom or deck to a new water heater or furnace. Page 9 of IRS Publication 523 has a list of eligible improvements.

There are limitations. The improvements must still be evident when you sell. So if you put in wall-to-wall carpeting 10 years ago and then replaced it with hardwood floors five years ago, you can’t count the carpeting as a capital improvement. Repairs, like painting your house or fixing sagging gutters, don’t count. The IRS describes repairs as things that are done to maintain a home’s good condition without adding value or prolonging its life.

There can be a fine line between a capital improvement and a repair, says Erik Lammert, former tax research specialist at the National Association of Tax Professionals. For instance, if you replace a few shingles on your roof, it’s a repair. If you replace the entire roof, it’s a capital improvement. Same goes for windows. If you replace a broken window pane, repair. Put in a new window, capital improvement.

One exception: If your home is damaged in a fire or natural disaster, everything you do to restore your home to its pre-loss condition counts as a capital improvement.

How Capital Improvements Affect Your Gain

To figure out how improvements affect your tax bill, you first have to know your cost basis. The cost basis is the amount of money you spent to buy or build your home including all the costs you paid at the closing: fees to lawyers, survey charges, transfer taxes, and home inspection, to name a few. You should be able to find all those costs on the settlement statement you received at your closing.

Next, you’ll need to account for any subsequent capital improvements you made to your home. Let’s say you bought your home for $200,000 including all closing costs. That’s the initial cost basis. You then spent $25,000 to remodel your kitchen. Add those together and you get an adjusted cost basis of $225,000.

Now, suppose you’ve lived in your home as your main residence for at least two out of the last five years. Any profit you make on the sale will be taxed as a long-term capital gain. You sell your home for $475,000. That means you have a capital gain of $250,000 (the $475,000 sale price minus the $225,000 cost basis). You’re single, so you get an automatic exemption for the $250,000 profit. End of story.

Here’s where it gets interesting. Had you not factored in the money you spent on the kitchen remodel, you’d be facing a tax bill for that $25,000 gain that exceeded the automatic exemption. By keeping receipts and adjusting your basis, you’ve saved about $5,000 in taxes based on the  15% tax rate on capital gains. Well worth taking an hour a month to organize your home improvement receipts, don’t you think?

The top rate for most homesellers remains 15%. For sellers in the 39.6% income tax bracket, the cap gains rate is 20%.

Watch Out for These Basis-Busters

Some situations (below) can lower your basis, thus increasing your risk of facing a tax bill when you sell. Consult a tax adviser.

  • If you use the actual cost method and take depreciation on a home office, you have to subtract those deductions from your basis.
  • Any depreciation available to you because you rented your house works the same way.
  • You also have to subtract subsidies from utility companies for making energy-related home improvements or energy-efficiency tax credits you’ve received.
  • If you bought your home using the federal tax credit for first-time homebuyers, you’ll have to deduct that from your basis too, says Mark Steber, chief tax officer at Jackson Hewitt Tax Services.

Spring is Here!!

Fairhope is shining with beautiful spring flowers and gorgeous sunsets.  Our market is extremely healthy.  Buyers are out and inventory is down.  Since January we have had 574 homes to close with 391 presently under contract.  These stats are from Spanish Fort to Point Clear.  As you know this is the Eastern Shore of Mobile Bay.

It is a great time to sit back and enjoy this time of the year.  May 9th is ladies day in downtown Fairhope.  Shops will be open late with specials for all the ladies.

Don’t forget Live at Five–concert series at the Community College Outdoor Stage–4/26 will be the The Modern El Dorados, 5/12 Wet Willie and Magnolia Bayou and 5/17 The Tip Tops.  These concerts are free–just bringing your blankets or chairs.

Henry Ford once said “Coming together is a beginning. Keeping together is progress. Working together is success.”

How this saying fits with real estate but also in all walks of life. This past Friday was of course the first Friday of the month but in FAIRHOPE it is “Art Walk”. Ashurst and Niemeyer’s downtown office on Section was open to our many clients as well as public. Music was provided by Jeff Farrow, who was incredible. Thank you for all that dropped by. This night was a tremendous success.

If you have not attended Art Walk, please put it on your calendar. You can start at the Art Center and stroll throughout the town. Be sure to make reservations for dinner to top off your evening. Fairhope is a truly wonderful place to live.

Home Value: Walmart and Surf Breaks?

9 Surprising Things That Add Value to Your Home

A home’s value is dependent on many things. Here are nine factors you might not have thought about.

P370182-1-1_surf-break

What do surf breaks, Walmarts, and public transportation have in common? Being near any of them can add thousands to your home’s value.

At least that’s what various university researchers have found based on their evaluation of variables that could be influencing home prices. Their conclusions might surprise you. Here’s what they found:


1. Surf Breaks

Being within a mile of a surf break (a spot where surf-able waves happen) adds about $106,000 to a home’s value, according to surfonomics experts at the Monterey Institute of International Studies.

Reality check: Mother Nature makes surf breaks, so it’s not like you could build your own DIY break to boost your home’s value.


2. Parks and Open Spaces

A desirable public park or other recreational open space boosts the property value of nearby homes by 8%-20%.

One study looked at 16,400 home sales within 1,500 feet of 193 public parks in Portland, Ore., and found these boosts to home values:

  • Natural areas: $10,648
  • Golf courses: $8,849
  • Specialty parks: $5,657
  • Urban parks: $1,214

Reality check: A park that’s not maintained and overcrowded can drag down nearby home values.


3. Living Near a Walmart

Along with making it easier to run out for a gallon of milk at midnight, researchers at the University of Chicago concluded that living within a mile of a Walmart store could raise your home’s value by 1%-2%, and living within half a mile could boost your property value by an additional 1%.

For an average-size home, that’s an uptick of $4,000-$7,000.

Realty check: What you gain in home value, you may end up spending at Walmart.


4. Solar Photovoltaic Systems

California homes with solar photovoltaic (PV) systems sell for a $17,000 premium over homes without solar systems, according to research from the U.S. Department of Energy’s Lawrence Berkeley National Laboratory.

Reality check: Although costs for residential solar power systems are falling, they’re still rather pricey at $15,000-$40,000, depending on the size of your house.


5. Walkability

Being able to stroll to schools, parks, stores, and restaurants will raise your property value anywhere from $4,000-$34,000, says a 2009 study from CEOs for Cities.

Reality check: The biggest boost in walkability values occurred in large, dense cities.


6. Accessory Dwelling Units

Whether it’s a granny flat, an in-law apartment, or a carriage house, having a separate unit can increase your home’s value by 25%-34%, according to a study of 14 properties with accessory dwelling units in Portland, Ore. You can also get a steady stream of income from a second unit.

Reality check: Local governments often ban accessory dwelling units, so check zoning laws, building codes, and homeowners association rules before you add a unit.


7. Professional Sports Arenas

A new pro sports stadium can raise property values in a 2.5-mile radius by an average of $2,214. The closer you are to the new facility, the larger the increase in home value. Researchers from the University of Illinois at Urbana-Champaign and the University of Alberta examined house sales in Columbus, Ohio, before and after the city added two sports stadiums.

Reality check: If a stadium is proposed, home values can decline a bit until the project is complete. And if you live really close to a stadium, you may encounter traffic and parking issues.


8. Community Gardens

Planting a community garden raises the value of homes within a 1,000-foot radius by 9.4% within five years, according to research by the Office of the Comptroller of the Currency and New York University School of Law.

The impact increases over time, and high-quality community gardens have the greatest positive influence. Poor neighborhoods saw the biggest gains in home values.

Reality check: Gardens on privately owned land and in higher-income neighborhoods don’t have the same beneficial influence.


9. Trees

No real surprise here — whether trees are in your yard or just on your street, they’re a valuable asset you should be aware of. Here’s a gauge of how much trees are worth to your home value according to a University of Washington research survey:

  • Mature trees anywhere in your yard: 2%.
  • Mature trees on your street: 3%.
  • Trees in your front yard: 3%-5%.
  • Mature trees in high income neighborhoods: 10%-15%.

Reality check: Trees usually mean work — raking leaves, trimming branches, and keeping roots out of sewer lines.


Be Sure You Get All Your Tax Benefits

Don’t miss these home tax deductions

From mortgage interest to property tax deductions, here are the tax tips you need to get a jump on your returns.
Home tax deduct

Owning a home can pay off at tax time. 

Take advantage of these homeownership-related tax deductions and strategies to lower your tax bill:

Mortgage Interest Deduction

One of the neatest deductions itemizing homeowners can take advantage of is the mortgage interest deduction, which you claim on Schedule A. To get the mortgage interest deduction, your mortgage must be secured by your home — and your home can be a house, trailer, or boat, as long as you can sleep in it, cook in it, and it has a toilet.

Interest you pay on a mortgage of up to $1 million — or $500,000 if you’re married filing separately — is deductible when you use the loan to buy, build, or improve your home.

If you take on another mortgage (including a second mortgage, home equity loan, or home equity line of credit) to improve your home or to buy or build a second home, that counts towards the $1 million limit.

If you use loans secured by your home for other things — like sending your kid to college — you can still deduct the interest on loans up $100,000 ($50,000 for married filing separately) because your home secures the loan.

PMI and FHA Mortgage Insurance Premiums

You can deduct the cost of private mortgage insurance (PMI) as mortgage interest on Schedule A if you itemize your return. The change only applies to loans taken out in 2007 or later.

By the way, the 2014 tax season is the last for which you can claim this deduction unless Congress renews it for 2015, which may happen, but is uncertain.

What’s PMI? If you have a mortgage but didn’t put down a fairly good-sized downpayment (usually 20%), the lender requires the mortgage be insured. The premium on that insurance can be deducted, so long as your income is less than $100,000 (or $50,000 for married filing separately).

If your adjusted gross income is more than $100,000, your deduction is reduced by 10% for each $1,000 ($500 in the case of a married individual filing a separate return) that your adjusted gross income exceeds $100,000 ($50,000 in the case of a married individual filing a separate return). So, if you make $110,000 or more, you can’t claim the deduction (10% x 10 = 100%).

Besides private mortgage insurance, there’s government insurance from FHA, VA, and the Rural Housing Service. Some of those premiums are paid at closing, and deducting them is complicated. A tax adviser or tax software program can help you calculate this deduction. Also, the rules vary between the agencies.

Prepaid Interest Deduction

Prepaid interest (or points) you paid when you took out your mortgage is generally 100% deductible in the year you paid it along with other mortgage interest.

If you refinance your mortgage and use that money for home improvements, any points you pay are also deductible in the same year.

But if you refinance to get a better rate or shorten the length of your mortgage, or to use the money for something other than home improvements, such as college tuition, you’ll need to deduct the points over the life of your mortgage. Say you refi into a 10-year mortgage and pay $3,000 in points. You can deduct $300 per year for 10 years.

So what happens if you refi again down the road?

Example: Three years after your first refi, you refinance again. Using the $3,000 in points scenario above, you’ll have deducted $900 ($300 x 3 years) so far. That leaves $2,400, which you can deduct in full the year you complete your second refi. If you paid points for the new loan, the process starts again; you can deduct the points over the life of the loan. 

Home mortgage interest and points are reported on Schedule A of IRS Form 1040.

Your lender will send you a Form 1098 that lists the points you paid. If not, you should be able to find the amount listed on the HUD-1 settlement sheet you got when you closed the purchase of your home or your refinance closing.

Property Tax Deduction

You can deduct on Schedule A the real estate property taxes you pay. If you have a mortgage with an escrow account, the amount of real estate property taxes you paid shows up on your annual escrow statement.

If you bought a house this year, check your HUD-1 settlement statement to see if you paid any property taxes when you closed the purchase of your house. Those taxes are deductible on Schedule A, too.

Energy-Efficiency Upgrades

If you made your home more energy efficient in 2014, you might qualify for the residential energy tax credit.

Tax credits are especially valuable because they let you offset what you owe the IRS dollar for dollar for up to 10% of the amount you spent on certain home energy-efficiency upgrades. 

The credit carries a lifetime cap of $500 (less for some products), so if you’ve used it in years past, you’ll have to subtract prior tax credits from that $500 limit. Lucky for you, there’s no cap on how much you’ll save on utility bills thanks to your energy-efficiency upgrades.

Among the upgrades that might qualify for the credit:

  • Biomass stoves
  • Heating, ventilation, and air conditioning
  • Insulation
  • Roofs (metal and asphalt)
  • Water heaters (non-solar)
  • Windows, doors, and skylights

To claim the credit, file IRS Form 5695 with your return.

Vacation Home Tax Deductions

The rules on tax deductions for vacation homes are complicated. Do yourself a favor and keep good records about how and when you use your vacation home.

  • If you’re the only one using your vacation home (you don’t rent it out for more than 14 days a year), you deduct mortgage interest and real estate taxes on Schedule A.
  • Rent your vacation home out for more than 14 days and use it yourself fewer than 15 days (or 10% of total rental days, whichever is greater), and it’s treated like a rental property. Your expenses are deducted on Schedule E.
  • Rent your home for part of the year and use it yourself for more than the greater of 14 days or 10% of the days you rent it and you have to keep track of income, expenses, and allocate them based on how often you used and how often you rented the house.

Homebuyer Tax Credit

This isn’t a deduction, but it’s important to keep track of if you claimed it in 2008.

There were federal first-time homebuyer tax credits in 2008, 2009, and 2010.

If you claimed the homebuyer tax credit for a purchase made after April 8, 2008, and before Jan. 1, 2009, you must repay 1/15th of the credit over 15 years, with no interest.

The IRS has a tool you can use to help figure out what you owe each year until it’s paid off. Or if the home stops being your main home, you may need to add the remaining unpaid credit amount to your income tax on your next tax return.

Generally, you don’t have to pay back the credit if you bought your home in 2009, 2010, or early 2011. The exception: You have to repay the full credit amount if you sold your house or stopped using it as primary residence within 36 months of the purchase date. Then you must repay it with your tax return for the year the home stopped being your principal residence.

The repayment rules are less rigorous for uniformed service members, Foreign Service workers, and intelligence community workers who got sent on extended duty at least 50 miles from their principal residence.

Mortgage-Related Tax Deductions

Tax Deductions if You Bought, Sold, or Refinanced Your Home

When you took out a mortgage to buy your home, did you pay points? You may be able to deduct that prepaid interest on your federal tax return — but only if you meet a long list of rules.

mortgage tax deduct

The points you paid when you signed a mortgage to buy your home may help cut your federal tax bill. With points, sometimes called loan origination points or discount points, you make an upfront payment to get a particular rate from the lender.

Since mortgage interest is deductible, your points may be, too.
If you itemize your deductions on Schedule A of IRS Form 1040, you may be able to deduct all your points in the year you pay them.

Some high-income taxpayers have their total itemized deductions limited, including points. You can read more about that in the instructions for Schedule A.

Lucky for you, the IRS doesn’t care whether you or the homesellers paid the points. Either way, those points are your deduction, not the sellers’.

Tip: Tax law treats home purchase mortgage points differently from refinance mortgage points. Refinance loan points get deducted over the life of your loan. So if you paid $1,000 in points for a 10-year refinance, you’re entitled to deduct $100 per year on your Schedule A.


The Fine Print for Deducting Points

The IRS rules for deducting purchase mortgage points are straightforward, but lengthy. You must meet each of these seven tests to deduct the points in the year you pay them.

1. Your mortgage must be used to buy or build your primary residence, and the loan must be secured by that residence. Your primary home is the one you live in most of the time. As long as it has cooking equipment, a toilet, and you can sleep in it, your main residence can be a house, a trailer, or a boat.

Points paid on a second home have to be deducted over the life of your loan.

2. Paying points must be a customary business practice in your area. And the amount can’t exceed the percentage normally charged. If most people in your area pay one or two points, you can’t pay 10 points and then deduct them.

3. Your points have to be legitimate. You can’t have your lender label other things on your settlement statement, like appraisal fees, inspection fees, title fees, attorney fees, service fees, or property taxes as “points” and deduct them.

4. You have to use the cash method of accounting. That’s when you report your income to the IRS as it comes in and report your expenses when you pay them. Almost everybody uses this method for tax accounting.

5. You must pay the points directly. That is, you can’t have borrowed the funds from your lender to pay them. Any points paid by the seller are treated as being paid directly by you.

In addition, monies you pay, such as a downpayment or earnest money deposit, are considered monies out of your pocket that cover the points so long as they’re equal to or more than points. Say you put $10,000 down and pay $1,000 in points. The downpayment exceeds the points, so your points are covered and therefore you can deduct them if you itemize. If you were to put nothing down but you paid one point, that $1,000 wouldn’t be deductible.

6. Your points have to be calculated as a percentage of your mortgage. One point is 1% of your mortgage amount, so one point on a $100,000 mortgage is $1,000.

7. The points have to show up on your settlement disclosure statement as “points.” They might be listed as loan origination points or discount points.

Tip: You can also fully deduct points you pay (for the year paid) on a loan to improve your main home if you meet tests one through five above.


Where to Deduct Points

Figured out that your points are deductible? Here’s how you deduct them:

Your lender will send you a Form 1098. Look in Box 2 to find the points paid for your loan.

If you don’t get a Form 1098, look on the settlement disclosure you received at closing. The points will show up on that form in the sections detailing your costs or the sellers’ costs, depending on who paid the points.


Report your points on Schedule A of IRS Form 1040.

There are two things related to points that you can’t deduct:

1. Interest buy-downs your builder paid

Some builders put money in an escrow account (as a buyer incentive) that the lender taps each month to supplement your mortgage payment. Those aren’t considered points even though the money is used for an interest payment and it’s prepaid. You can’t deduct the money the builder put into that escrow account.

2. Interest payments from government programs

You can’t deduct points paid by a federal, state, or local program, such as the federal Hardest Hit Fund, to help you if you’re experiencing financial trouble.